A Fast, Reliable, and Nationwide Mortgage Solution
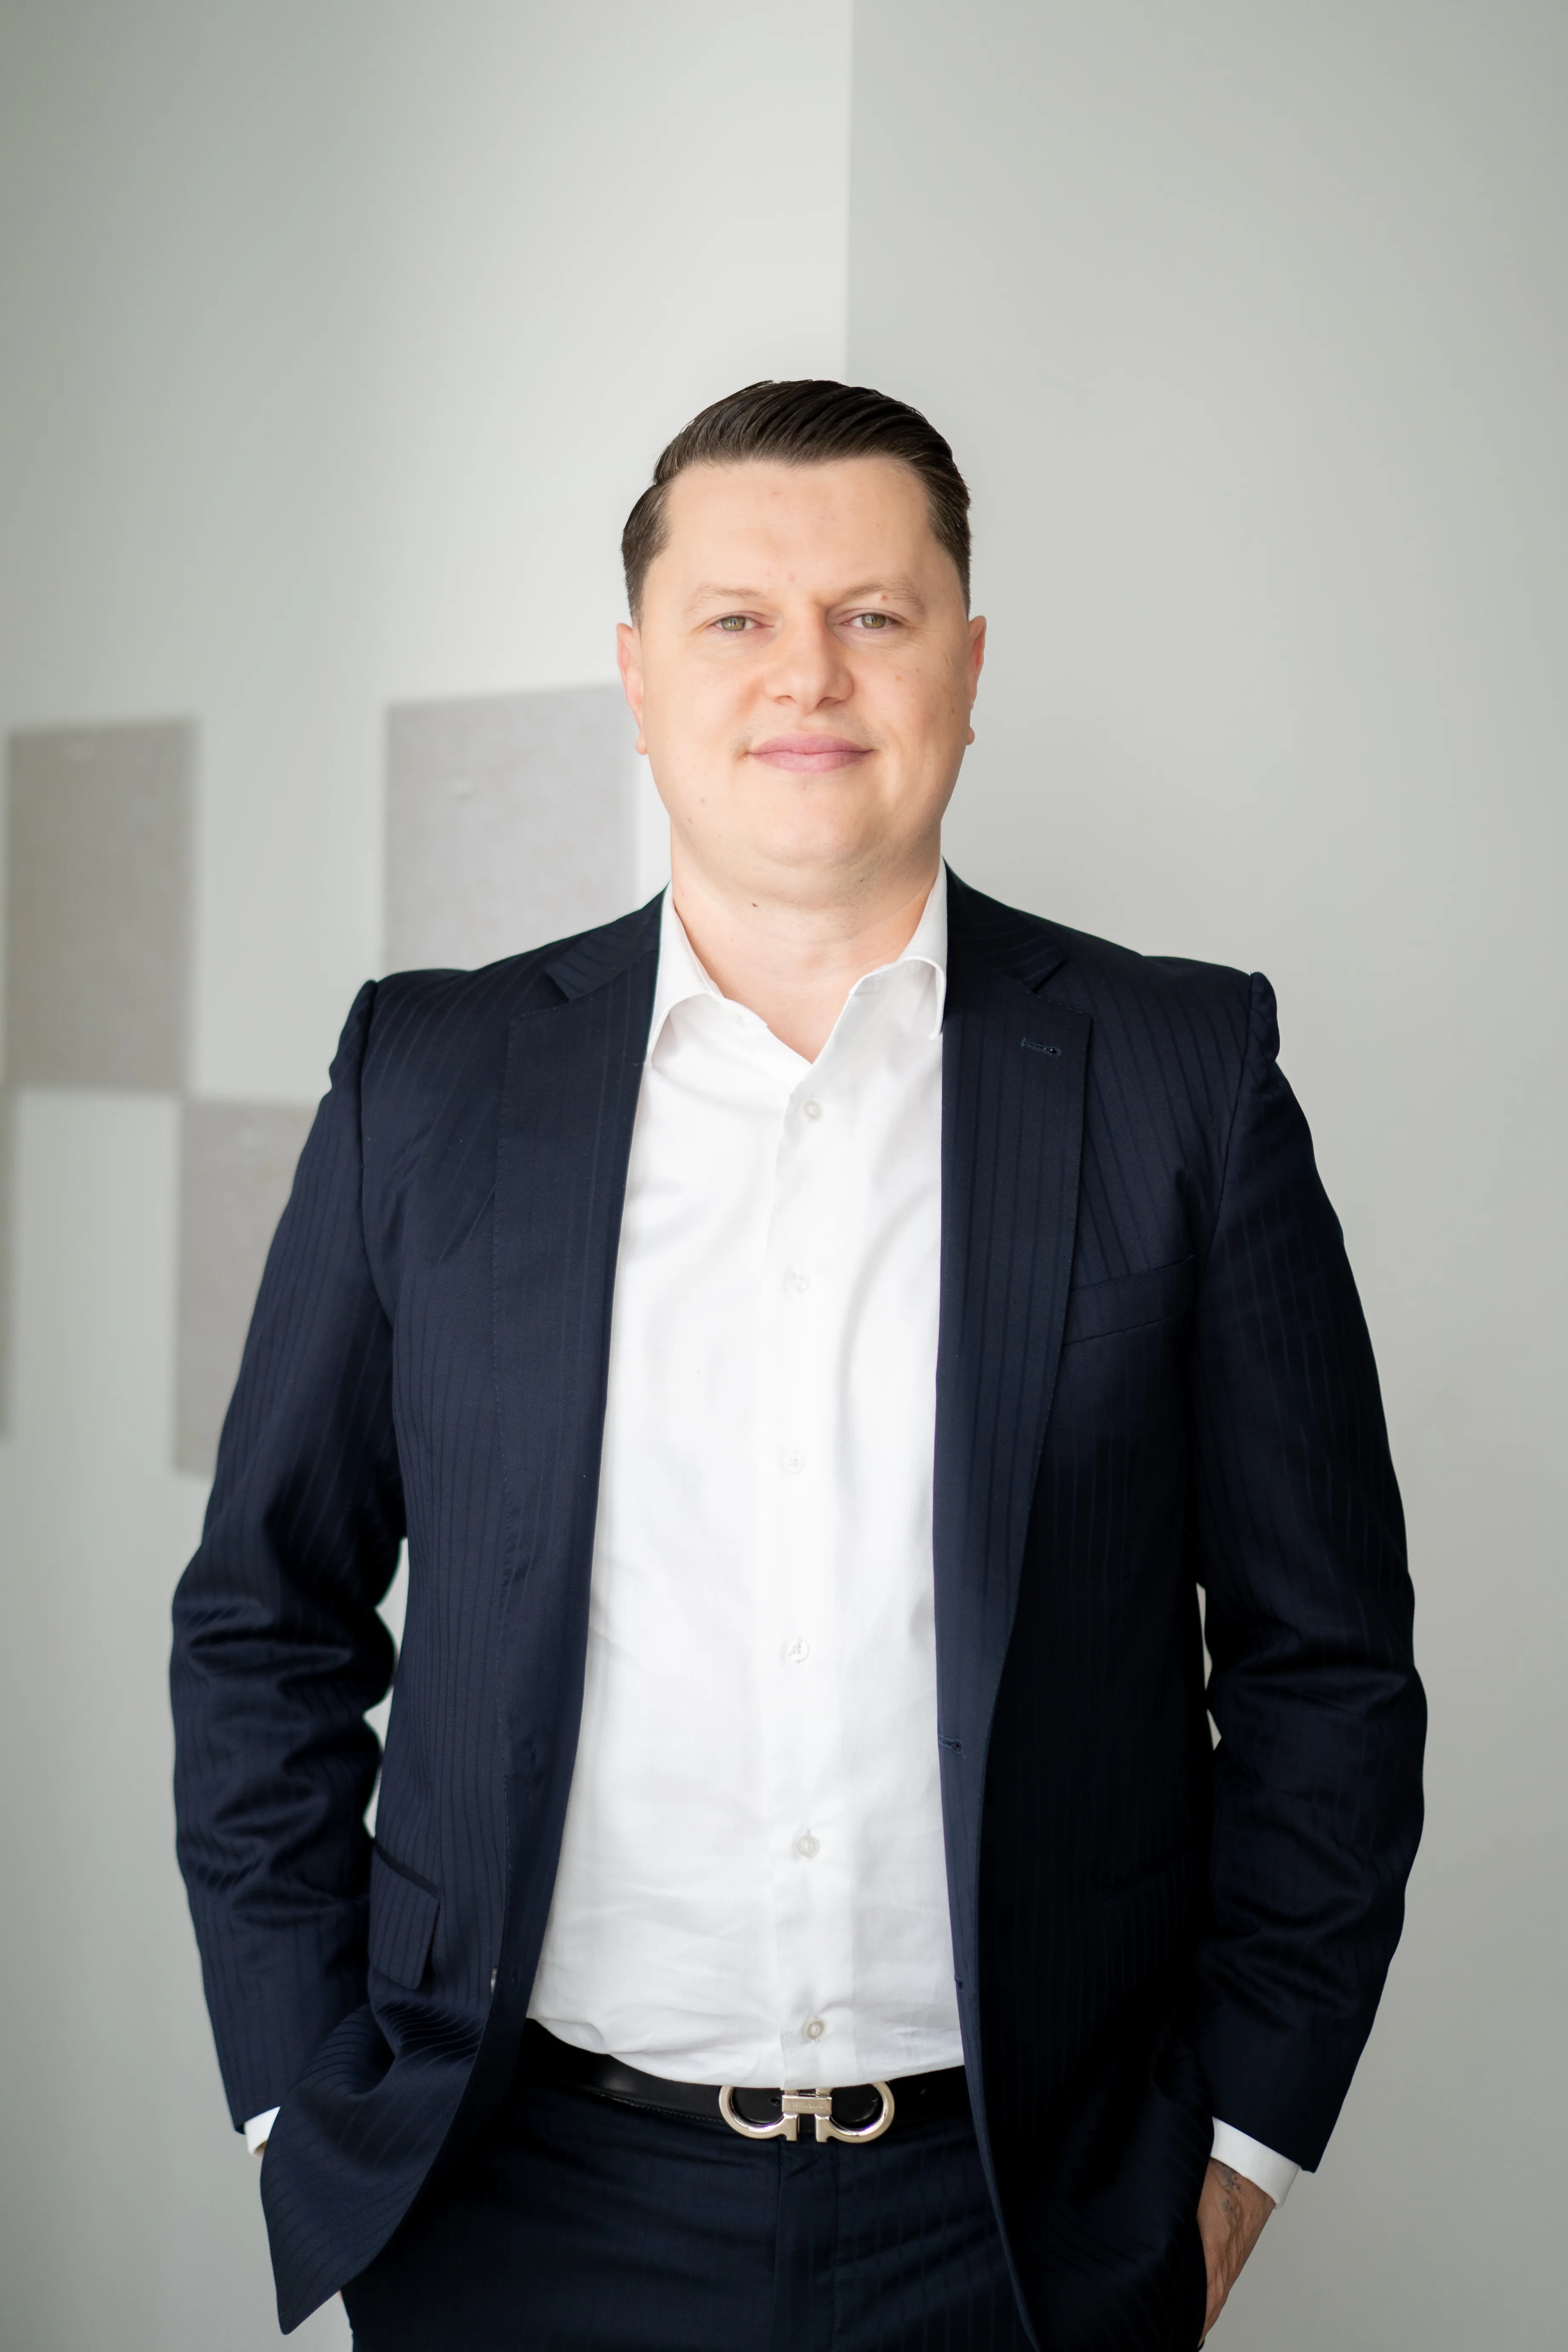
Uran Blakaj
Chief Executive Officer
Uran Blakaj is a seasoned mortgage executive with over a decade of leadership experience in residential lending and real estate. A graduate of Hunter College with a Bachelor of Science in Accounting, he combines financial expertise with strategic leadership and regulatory discipline.
As CEO and Loan Officer of UBM Capital Corp DBA Sprint Mortgage, Uran oversees loan origination, underwriting operations, and organizational strategy, driving operational excellence and compliance. Bilingual in English and Albanian, he is known for his analytical precision, client-focused approach, and commitment to long-term growth and trusted relationships.
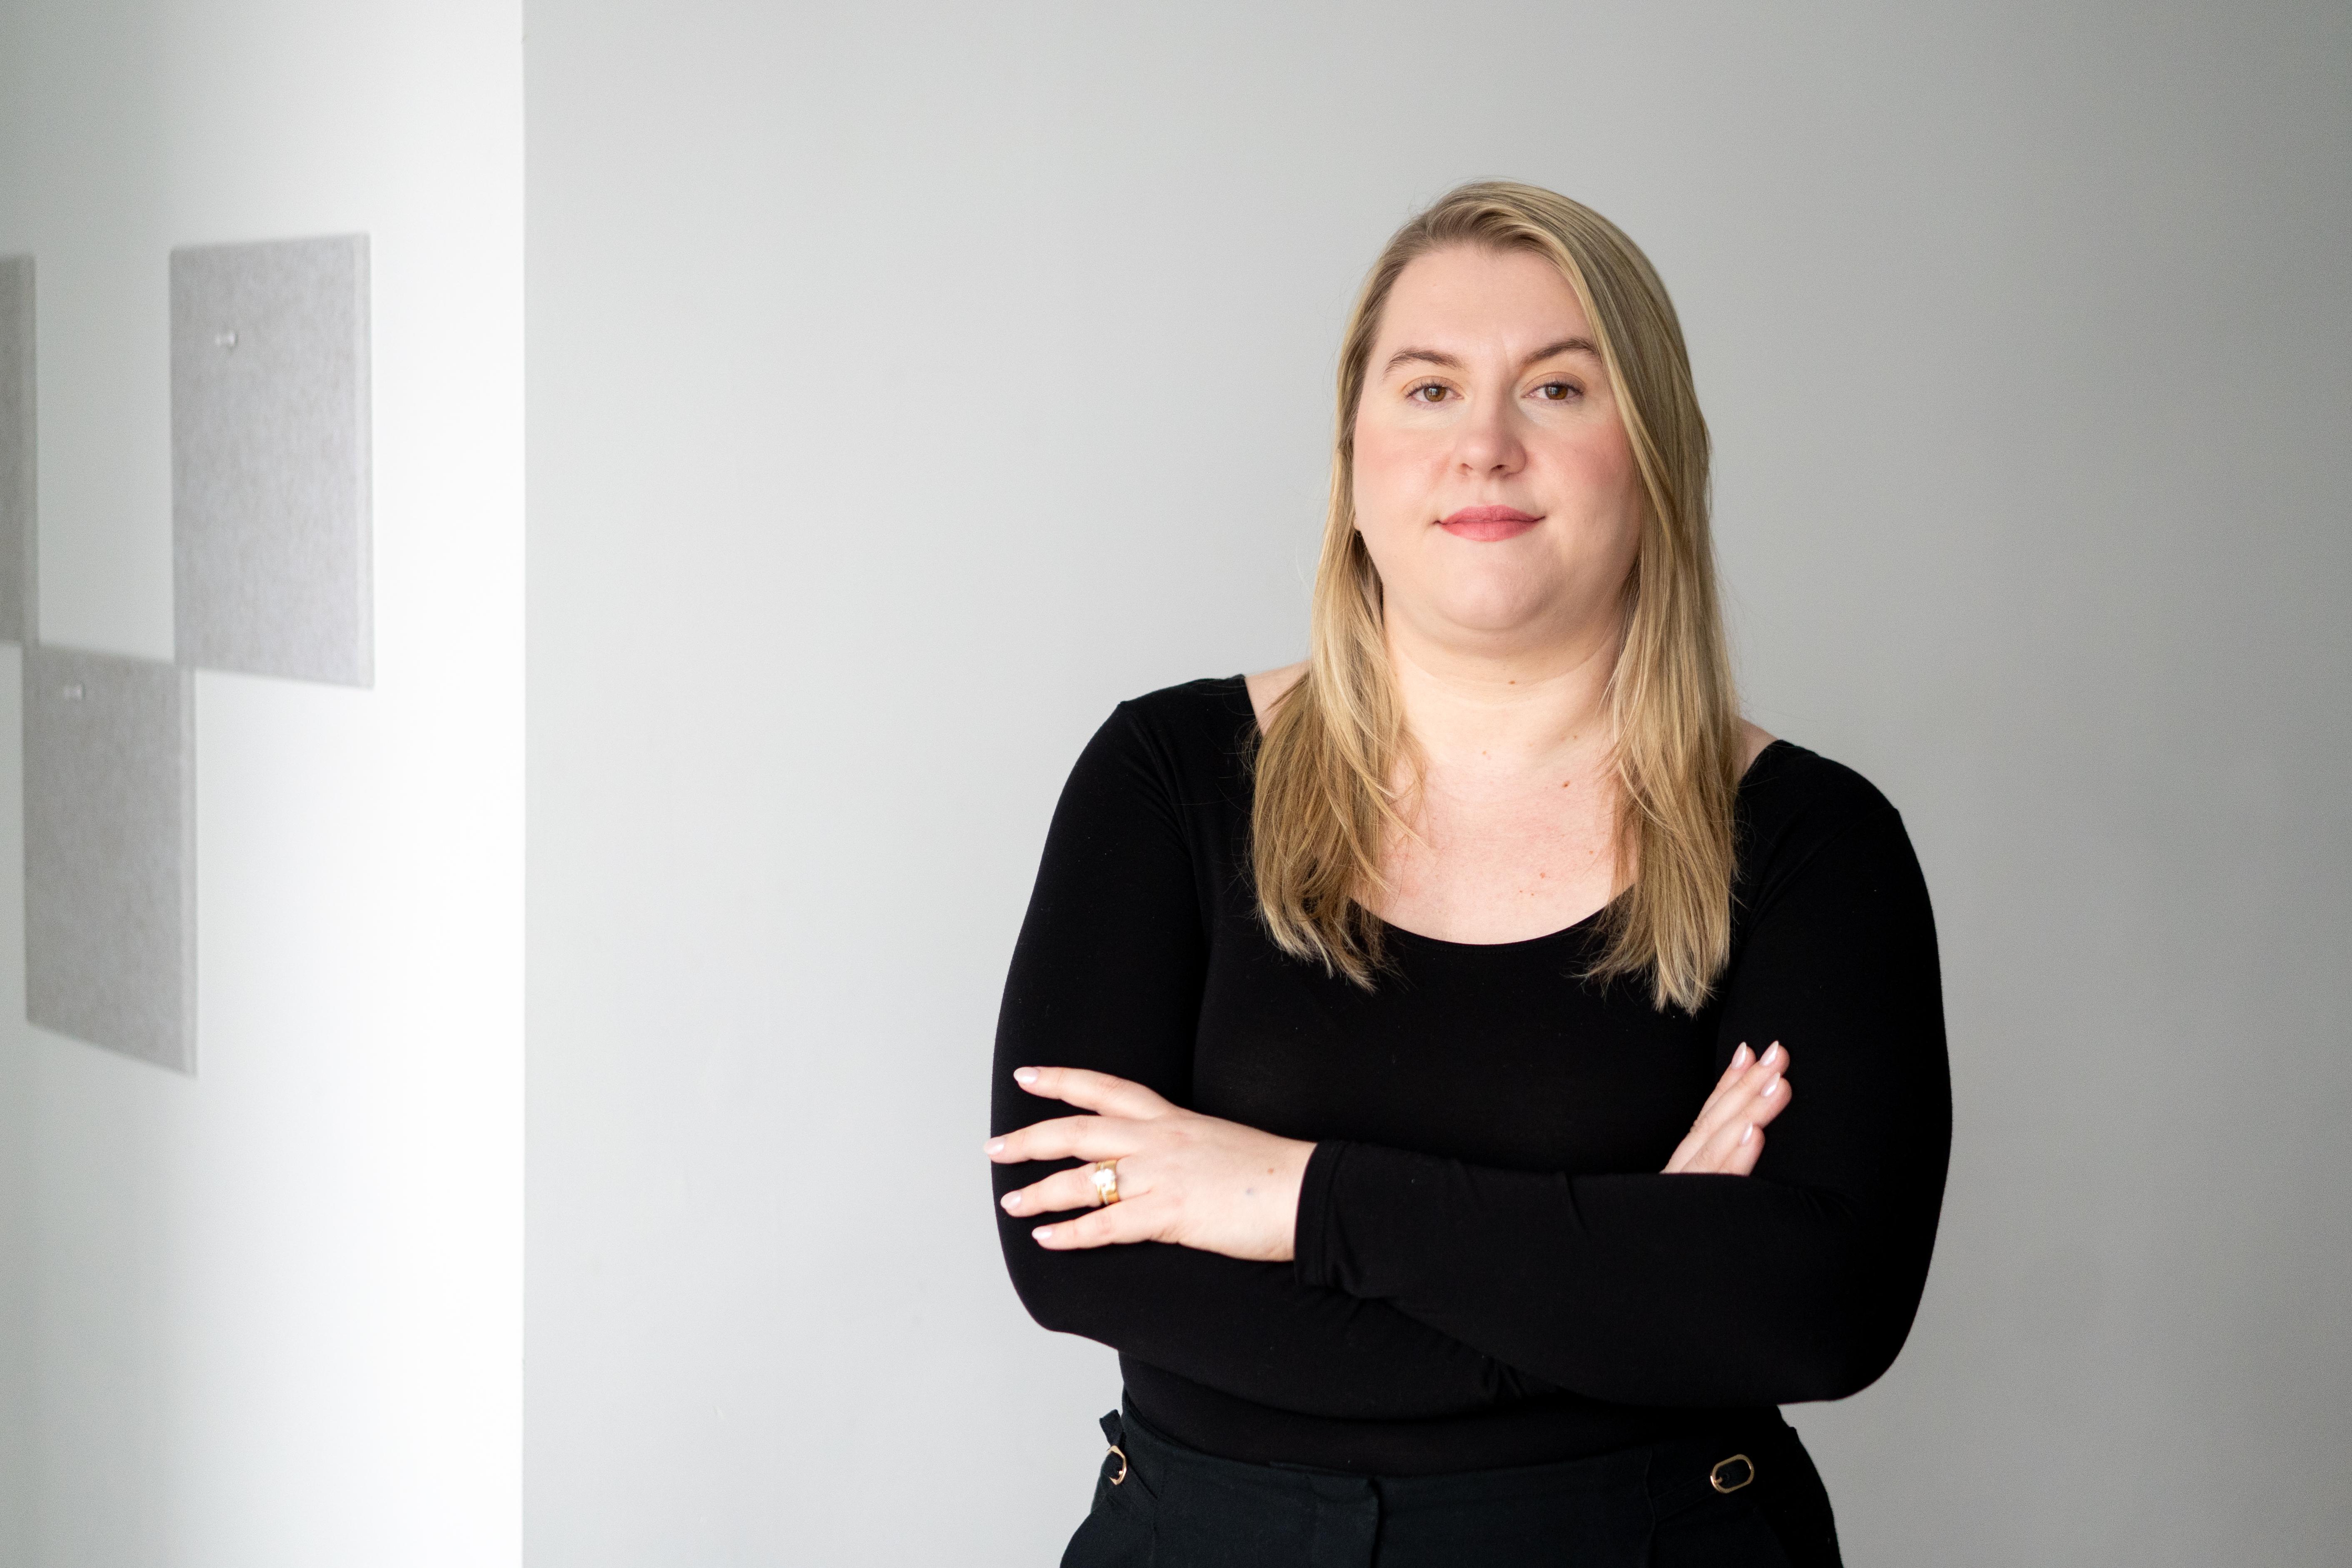
Urate Blakaj-Musovic
Chief Operating Officer
Urate Blakaj-Musovic has worked in the mortgage industry since 2018, with hands-on experience throughout the full loan process, including origination, processing, and closing. She has experience with conventional, FHA, and agency loans, as well as self-employed and business-owner income.
As a former tax business owner, Urate also brings valuable insight into taxes and complex financial documentation. Fluent in Albanian and English, she is dedicated to providing clear, personalized guidance to every client.
How to Join the Sprint Team
Sprint Mortgage is always on the lookout for talented loan officers who thrive in a fast-paced, team-oriented environment.
Frequently asked questions
We've compiled answers to the questions we hear most often. If you don't see what you're looking for, reach out — we're always happy to help.
A mortgage broker acts as a middleman between you and the lenders. Instead of applying to just one bank, we compare multiple lenders, rates, and loan options to find the one that best suits your needs. Our goal is to save you time, money, and stress during the home loan process.
Banks can only offer their own loan products. A broker has access to a wide range of lenders, which means more choices, better rates, and loan programs that may fit your unique situation. We also guide you step-by-step, making the process smoother and less overwhelming.
As a mortgage broker, we’re compensated by the lender — not by you. That means our guidance, lender shopping, and support throughout the process come at no direct cost to you as the borrower. We believe in full transparency, so if anything ever applies to your specific loan, we’ll tell you upfront — no surprises, ever.
Generally, you’ll need:
- Proof of income (pay stubs, W-2s, or tax returns if self-employed)
- Bank statements
- Photo ID
- Credit history
Every situation is unique, so we’ll provide a tailored checklist once we get started.
- Pre-qualification is a quick estimate of how much you might be able to borrow, based on basic information you provide.
- Pre-approval is a more detailed review by a lender, using your credit report and financial documents. Pre-approval carries more weight when making an offer on a home.
The traditional down payment is 20%, but many programs allow for much less. Some loans only require 3–5% down, and certain government-backed loans (like VA or USDA) may require no down payment at all. We’ll help you explore the best option for your budget.
Most lenders prefer a credit score of 620 or higher, but there are programs available for lower scores. Keep in mind that the higher your credit score, the better the interest rates and loan terms you’ll qualify for. We’ll review your options based on your unique credit profile.
Yes. Having less-than-perfect credit or being self-employed doesn’t automatically disqualify you. We work with a variety of lenders, some of whom specialize in helping clients with credit challenges or non-traditional income.
Upfront costs typically include:
- Appraisal fees
- Home inspection (if applicable)
- Title and attorney fees
- Lender fees
- Prepaid taxes and insurance
Closing costs usually range from 2–5% of the loan amount. We’ll provide a clear estimate early in the process so you know exactly what to expect.
The timeline can vary, but most loans close within 30–45 days once you’re under contract. Pre-approvals can often be completed in as little as 24–48 hours. We’ll keep you updated at every step so there are no surprises.